

Plynk: Grow as an Investor analysis by Appwee
I approached Plynk: Grow as an Investor as a finance app for people who want investing to feel less intimidating, not as a replacement for a full professional trading workstation. Its central appeal is the way it combines investing tools with learning material, so I can make decisions while gradually understanding the terms and choices in front of me. That focus gives the app a clear identity: it is trying to reduce confusion at the moment when a new investor is deciding what to do next.
The app is free, aimed at an Everyone audience, and developed by Digital Brokerage Services LLC. It belongs to the finance category and has reached more than half a million installs, with an average rating of 4.1 from roughly four thousand ratings. Those figures suggest that it has found a real audience, although they also tell me to keep expectations realistic: popularity does not turn an investing app into a guarantee of good results.
Learning while making an investment decision
The most important capability here is the connection between investing tools and education. Many finance apps separate those experiences. One screen shows prices and account actions, while learning happens somewhere else through articles, videos, or a course. Plynk’s approach is more useful for a beginner because the educational layer is meant to make the investing process easier to understand while I am already thinking about a financial choice.
That distinction matters. A beginner often does not need another wall of market information; they need a plain explanation of what a term means, why a choice exists, and what kind of decision they are making. When an app places education close to the investing workflow, it can help turn a vague impulse into a more deliberate action. In my view, that is the strongest reason to try this particular app.
I would not describe the experience as a shortcut to becoming an expert. Education can clarify concepts, but it cannot predict markets or remove risk. The useful effect is smaller and more practical: I can slow down, check my understanding, and avoid making a choice simply because a financial phrase sounds familiar. For someone opening an investment account for the first time, that reduction in uncertainty can be more valuable than a crowded screen full of advanced indicators.
The app’s current version is 4.4.2 and it requires iOS or Android version 12 or later. That operating-system requirement is worth checking before downloading, especially if I am using an older phone. On a compatible device, the free entry point makes it easier to test the learning style without committing money to a subscription just to see whether the interface suits me.
What this capability changes for a beginner
When I use an investing app that assumes I already know the vocabulary, I tend to postpone decisions or copy what other people appear to be doing. Plynk’s education-centered design is better suited to replacing that passive behavior with a basic process: understand the idea, consider the purpose, and then decide whether the action fits my own situation.
A useful habit is to treat each educational explanation as a prompt for a question rather than as a recommendation. If the app explains a type of investment, I would ask myself what role it would play in my plan, how comfortable I am with losses, and whether I understand what I am buying. This is one of the non-obvious strengths of the app: it can become a decision checkpoint, not merely a place to press a button.
There is also a trade-off. A simplified explanation may be easier to read, but it cannot cover every exception or personal circumstance. I would use the educational material to build a foundation, then verify important details through reliable financial resources before committing a meaningful amount of money. The app is most helpful when it improves my questions, not when I treat it as the only source of answers.
How the experience works in everyday use
My practical approach would begin with a small, clearly defined goal. Instead of opening the app with the vague intention to “start investing,” I would decide whether I am learning basic investing language, exploring an option for long-term saving, or simply becoming familiar with the workflow. That goal changes how I read the educational content. It also prevents the common mistake of browsing financial products without knowing what problem I am trying to solve.
The next step is to move slowly through the information presented around a potential investment. I would pay attention to the explanation, identify unfamiliar terms, and write down anything that still feels unclear before taking action. This sounds simple, but it is a meaningful workflow improvement. The app becomes a place where I can prepare a decision instead of a place where I react to a price movement.
For a first-time user, I recommend separating learning sessions from money decisions. I might spend one session exploring how the app explains investing, then return later after considering my budget and time horizon. That pause is especially valuable because a friendly interface can make investing feel easier than it really is. The design may reduce friction, but the underlying financial risk remains.
A realistic example would be someone with a regular paycheck who wants to understand investing before setting aside a modest amount each month. They could use Plynk to become comfortable with basic concepts during a quiet evening, note which terms need more research, and only then decide whether the app fits their next step. The benefit is not that the app makes the decision for them. The benefit is that the decision can become more informed and less rushed.
A workflow I would recommend
Start by defining the purpose of the money rather than browsing investments immediately. Money needed soon should be treated differently from money intended for a distant goal.
Use the educational material to clarify unfamiliar language, then restate the idea in your own words. If you cannot explain it simply, I would not invest in it yet.
Keep the first amount small enough that normal market movement will not disrupt your essential budget. A comfortable learning experience is not the same as a risk-free investment.
Review your reasoning after the decision. Ask whether you chose something because it matched your goal or because the process made it feel exciting and easy.
This workflow highlights a strength that is easy to overlook: the app can support better behavior through pacing. It does not need to provide every advanced tool to be useful. For a new investor, learning to pause and explain a decision may be more important than learning to interpret a complex chart.
Where the simple approach can feel limited
The same clarity that helps beginners may feel restrictive to experienced investors. Someone who wants deep research, detailed portfolio analysis, specialized order controls, or a broad professional dashboard may outgrow the app’s teaching-first approach. I would not choose it as my only finance tool if my routine depends on advanced analysis or frequent, highly specific trading decisions.
There is another practical limitation: education can take time. If I want to complete a transaction quickly, reading through explanations may feel like an obstacle rather than a benefit. That is not necessarily poor design; it is a consequence of the app’s central philosophy. Plynk is asking me to understand more before acting, while some alternatives are optimized for speed.
I also would not confuse a clean interface with personal financial guidance. An app can present information clearly without knowing my income, debts, emergency savings, tax situation, or long-term plans. Those factors belong in my own decision-making process. If I need individualized advice, I would look beyond a general investing app and speak with a qualified professional.
The best scenario for using Plynk
The strongest use case is a cautious beginner who wants to start learning and investing in the same place. This person may recognize that leaving money idle is not the only option, but may feel uncomfortable with financial jargon and does not want a professional-looking platform that assumes prior knowledge. The app’s combination of intuitive tools and education is directly suited to that gap.
It could also work for someone who has tried investing content elsewhere but found it too abstract. Reading general explanations can be useful, yet many people understand a concept better when it is connected to an actual decision. Plynk’s approach gives the lesson a practical context. I can learn what a term means and immediately think about why it might matter to my own plan.
Another good scenario is a shared learning routine between a parent and an adult child, or between friends who are each building their own understanding. The app should not replace independent judgment, but its approachable format can make it easier to discuss basic concepts without one person needing to act as the expert. I would still keep accounts and decisions personal, while using the educational experience as a starting point for conversation.
For a busy user, the app may be most useful in short sessions rather than long research marathons. I would set aside a few minutes to learn one concept, record the question it raises, and return when I have enough attention to make a careful decision. That approach prevents the app from becoming another source of financial scrolling and keeps the learning tied to a clear purpose.
When another option may be better
I would choose a different type of platform if my main need were advanced market analysis, highly detailed reporting, or a large set of professional controls. A full-service brokerage can be a better fit for an experienced investor who already understands the basics and wants more depth. An independent educational resource may also be preferable if I want broad financial planning guidance rather than lessons connected to one investing workflow.
I would also skip Plynk as my primary choice if I am looking for guaranteed returns or a way to avoid losses. No investing interface can provide that. A savings product may be more appropriate for money that must remain stable and accessible, while investing should generally be considered only for funds that can tolerate market uncertainty and a longer time frame.
Finally, I would not download it simply because it is free. Free access removes one barrier, but it does not remove the need to understand what I am doing. The right question is whether the app’s educational style helps me make calmer, more informed choices than the alternatives I already use.
Trade-offs that matter before you begin
The first trade-off is simplicity versus depth. Plynk’s approachable presentation is likely to help someone who feels lost in a traditional brokerage interface. The cost is that users seeking extensive customization may find the experience less satisfying. I see this as a deliberate focus rather than a flaw, but it still affects who should choose the app.
The second is guidance versus independence. Educational prompts can help me understand a decision, yet they may also create a false sense that I am being guided personally. I need to remain responsible for checking whether an investment suits my goals and risk tolerance. The app can make the path clearer, but I still have to choose the destination.
The third is convenience versus reflection. A smooth mobile workflow makes it easy to return regularly, which can be helpful for building a learning habit. It can also make impulsive behavior easier if I open the app whenever the market is moving. My practical safeguard would be to decide in advance how often I review investments and avoid turning every price change into a reason to act.
One more trade-off concerns device compatibility. Because the app requires a relatively recent operating-system version, users on older phones may need to update their device software or use another service. Before planning around it, I would check compatibility and make sure the phone can handle the current app version comfortably.
The public response is encouraging but not perfect: the app carries a 4.1 average from about four thousand ratings and has around six hundred written reviews. I read that as evidence of broad usefulness with room for individual differences. Some people will appreciate the clarity, while others will want more sophistication or a different investing workflow.
Who gains the most from this approach
I think Plynk is best for a new or returning investor who values explanation as much as execution. If I want to understand the basics, build confidence gradually, and avoid feeling overwhelmed by a conventional brokerage screen, this app has a sensible focus. Its free availability makes experimentation easier, and the Everyone age rating keeps the presentation approachable for a broad audience.
It is also a good fit for someone who learns by doing, provided they can keep learning separate from impulse. The app’s strongest contribution is not a promise of better market performance. It is the chance to connect a financial concept with a real decision and then approach that decision with more awareness.
Experienced investors may still find a role for it as a simple learning-oriented companion, but I would not expect it to replace a more complete platform. People who need personalized advice, extensive research, or advanced controls should look elsewhere or use Plynk alongside a service designed for those needs.
After reviewing the app through that lens, my recommendation is measured but positive. Choose Plynk if your biggest obstacle is understanding how to begin. Use its education to slow down, question your assumptions, and develop a repeatable process. Do not choose it expecting certainty, instant expertise, or a substitute for personal financial planning. For the right beginner, that honest balance is exactly what makes the app useful.
Gallery
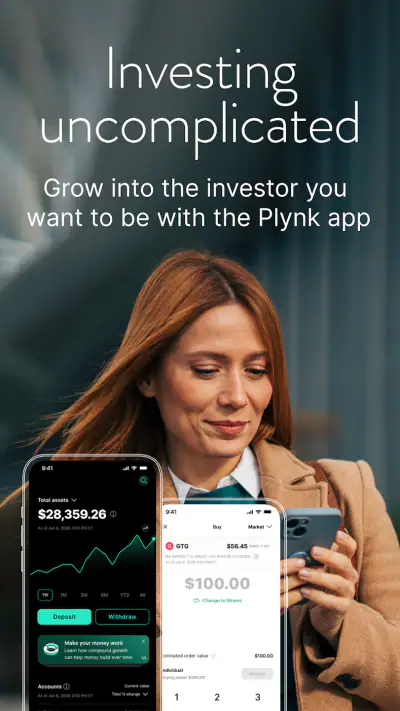
Plynk: Grow as an Investor Pros and Cons
- Simple interface makes investing approachable for beginners.
- Fractional shares let users start with relatively small amounts.
- Educational content helps explain basic investing concepts.
- Automated features can make regular investing more convenient.
- Supports diversified portfolios across multiple investment options.
- Investment choices may be more limited than on larger broker platforms.
- Market investments can lose value
- including the money you deposit.
- Fees or spreads may reduce returns depending on the selected service.
- Advanced trading tools and analysis are limited for experienced investors.
- Availability and account features may vary by country and eligibility.
Plynk: Grow as an Investor Frequently Asked Questions
What is Plynk: Grow as an Investor?
Plynk: Grow as an Investor is an investing app designed to make the stock market and other investment options easier to understand. It combines educational explanations with a simplified investing experience, allowing users to explore companies, funds, and market ideas without being overwhelmed by complex financial terminology. It is aimed primarily at beginners who want to learn while building an investment habit.
Can beginners use Plynk to start investing?
Yes, Plynk is built with new investors in mind and presents investing concepts in a clear, approachable way. The app generally guides users through account setup, risk-related questions, and available investment choices before they place an order. However, beginner-friendly design does not remove investment risk, so users should understand what they are buying and avoid investing money they may need in the short term.
What can I invest in through Plynk?
The investment choices available through Plynk may include individual shares, exchange-traded funds, and other supported products, depending on the user’s location and account eligibility. The app typically provides basic information to help compare opportunities, but it should not be treated as a guarantee of performance. Availability, fees, minimums, and account features can change, so checking the current in-app details is important.
Does Plynk charge fees for using the app?
Plynk may use a fee structure that varies according to the account type, services used, and the user’s region. Some activities may be free, while other transactions or optional features could involve charges. Before confirming an investment, review the latest pricing information, including possible fund expenses, currency conversion costs, or withdrawal-related fees, because these costs can affect long-term returns.
Is money invested through Plynk protected if the market falls?
No investing app can protect users from normal market losses. The value of shares, funds, and other investments can rise or fall, and you may receive less than you invested when selling. Plynk may operate with regulated financial partners and offer protections that apply to eligible cash or assets under local rules, but those protections generally do not cover losses caused by market performance.














